By Cliff Potts, CSO, and Editor-in-Chief of WPS News
Baybay City, Leyte, Philippines — September 14, 2026 — 17:35
The financial crisis of 2007–2008 forced a choice.
Stabilize the system, or protect the people inside it.
In practice, the response prioritized stabilization. The financial system was secured quickly and decisively. The recovery for ordinary households was slower, more uneven, and in many cases incomplete.
That distinction defines the legacy of the crisis response.
The Promise of Change
The 2008 election cycle was built around the idea of transformation.
Voters were not looking for continuity. They were looking for a break from the policies and assumptions that led to the collapse. The expectation, fairly or not, was that the response would resemble structural reform rather than system preservation.
There is nothing inherently wrong with a moderate or pragmatic approach to governance. Stability has value. Continuity has value.
The issue in 2009 was not moderation itself.
It was the gap between what was promised and what was delivered.
Stabilizing the System
When the crisis hit, the financial system was at risk of cascading failure.
The response from the administration of Barack Obama focused on preventing that outcome. Major financial institutions were stabilized. Liquidity was restored. Confidence, at least within the markets, began to return.
This approach reflected a clear policy priority: prevent systemic collapse first.
During this period, White House Chief of Staff Rahm Emanuel described the strategy as “foaming the runway,” an aviation term referring to preparing for a controlled emergency landing.
The system would land safely.
That was the objective.
“Foaming the Runway”
The metaphor matters because it reveals the mindset.
In an aviation emergency, the priority is not to assign blame midair. It is to ensure the aircraft lands without catastrophic loss. In financial terms, that meant stabilizing the institutions at the center of the crisis.
In practice, this approach ensured that banks were supported quickly and decisively.
Whether households would land safely was treated as a separate problem.
Homeowners and the Limits of Relief
Relief programs for homeowners existed. On paper, they were intended to slow foreclosures and allow borrowers to remain in their homes.
In practice, their design limited their effectiveness.
Participation required extensive documentation, repeated verification, and cooperation from lenders and mortgage servicers. Borrowers were often told that paperwork they had already submitted was missing, incomplete, or needed to be sent again. Trial modifications frequently failed to convert into permanent solutions, and the process became notorious for delays, contradictory instructions, and lost documents at the servicing level (ProPublica, 2010).
Many households did not simply choose to walk away.
They encountered a process that was prolonged, uncertain, and difficult to complete, contributing to continued foreclosures even as intervention efforts were underway.
At the same time, lending practices in the years leading up to the crisis had distributed risk widely throughout the financial system through high-risk mortgage products and securitization structures.
Borrowers were required to navigate complex requirements to obtain relief.
Financial institutions were stabilized more directly.
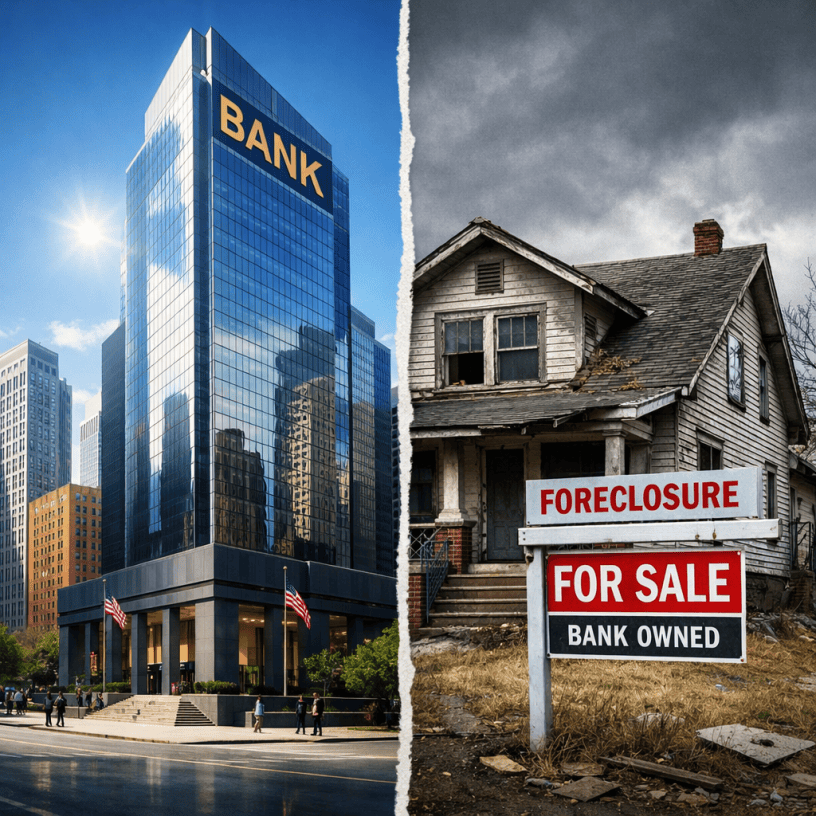
Two Standards in One Crisis
The contrast was not subtle.
Financial institutions were encouraged to stabilize, supported by existing legal and administrative capacity, and provided with relatively direct access to relief mechanisms. They had the expertise, representation, and infrastructure necessary to navigate that process successfully.
Individual homeowners, by comparison, were required to navigate a fragmented and often opaque system, frequently without meaningful assistance. They were asked to document, re-document, and re-qualify, often while under financial and emotional stress.
The result was not simply uneven recovery.
It was the application of two different standards within the same crisis.
The Accountability Gap
The scale of the crisis raised expectations of accountability.
Those expectations were not widely met.
Despite widespread evidence of risky and, in some cases, abusive lending practices, relatively few senior figures within the financial sector faced individual legal consequences tied directly to the collapse.
Penalties were often institutional rather than personal.
For many observers, the conclusion was difficult to avoid: the system had the capacity to absorb losses, but limited capacity to assign responsibility at the highest levels.
A Matter of Governing Philosophy
Barack Obama later observed that his policy positions might have been considered those of a “moderate Republican” in an earlier political era.
There is nothing inherently wrong with that orientation.
But it helps explain the response.
A pragmatic, system-preserving philosophy will prioritize stability, continuity, and incremental change. It will avoid disruption where possible, even when disruption is what some voters expected.
That approach stabilized the system.
It did not produce equal protection for those affected by its failure.
What Was Protected
The financial system recovered.
Markets stabilized. Institutions regained footing. Confidence returned at the top of the economic structure.
Households experienced a different trajectory.
Recovery took longer. Losses in housing, savings, and opportunity were not fully restored for many. Time, once lost, could not be recovered.
The system was stabilized first.
For many households, recovery was slower, more burdensome, and far less secure.
References
Congressional Oversight Panel. (2009–2011). Oversight reports on the Troubled Asset Relief Program (TARP).
Obama, B. (2012). Interview on political ideology and historical comparison of policy positions.
ProPublica. (2010). By the numbers: A revealing look at the mortgage modification effort.
U.S. Department of the Treasury. (2009). Making Home Affordable Program guidelines.
White House. (2009). Statements and briefings on financial stabilization strategy.
Discover more from WPS News
Subscribe to get the latest posts sent to your email.
 WPS News
